This guidance will help stakeholders understand how to reference IFRS Accounting Standards to follow recent updates to the IFRS Foundation® Trade Mark Guidelines. This guidance clarifies how auditors or practitioners should refer to the IFRS Accounting Standards in their reports.
The International Auditing and Assurance Standards Board (IAASB) today published the International Standard on Auditing for Audits of Financial Statements of Less Complex Entities, known as the ISA for LCE. The ISA for LCE is a standalone global auditing standard designed specifically for smaller and less complex businesses and organizations. Built on the foundation of the International Standards on Auditing (ISAs), audits performed using this standard provide the same level of assurance for eligible audits: reasonable assurance. The standard is effective for audits beginning on or after December 15, 2025 for jurisdictions that adopt or permit its use.
“The ISA for LCE underscores the IAASB’s commitment to ensuring the credibility and reliability of financial reporting for entities of all sizes. By leveraging the International Standards on Auditing as our starting point, we are cultivating an environment where audits are performed in a globally consistent and high-quality way for the smallest entities. The IAASB’s actions seek to inspire greater confidence and contribute to the overall stability and trustworthiness of information in the external reporting ecosystem. We have also heard that this standard should provide an impetus for the evolution of auditing in developing economies,” said IAASB Chair Tom Seidenstein. “We now turn to each jurisdiction and their oversight authorities and regulators to decide whether to adopt the standard. We encourage practitioners and others to reach out to the authorities in their jurisdictions to advocate for the ISA for LCE’s adoption.”
Released alongside the ISA for LCE are a Basis for Conclusions, which details feedback from the public consultation period, a high-level fact sheet, and a frequently asked questions document. Additional materials to help jurisdictions navigate adoption will be issued in 2024, including supplementary guidance, a fact sheet on adoption, and a first-time implementation guide. All materials can be accessed on the IAASB website: iaasb.org/ISAforLCE
The ISA for LCE is a standalone global auditing standard designed specifically for smaller and less complex businesses and organizations. Built on the foundation of the International Standards on Auditing, audits performed using this standard provide the same level of assurance for eligible audits: reasonable assurance.
The standard is effective for audits beginning on or after December 15, 2025 for jurisdictions that adopt or permit its use.
Have you heard? We have a new standard for audits of less complex entities—known as ISA for LCE—coming on December 6. Learn more about it in our new video.
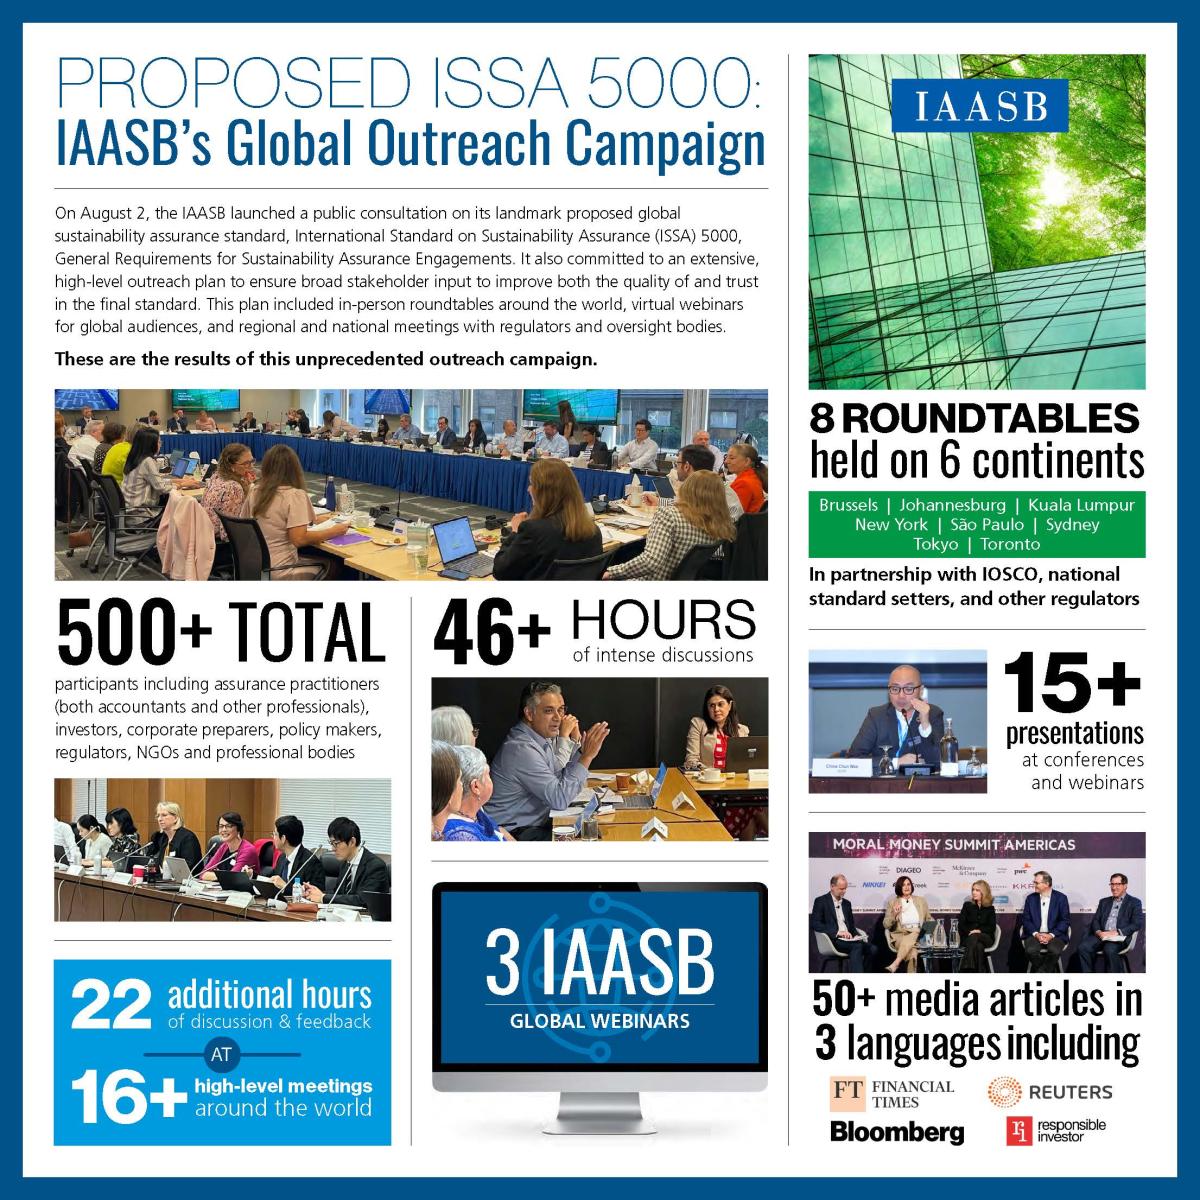
On August 2, the International Auditing and Assurance Standards Board (IAASB) launched a public consultation on its landmark proposed global sustainability assurance standard, International Standard on Sustainability Assurance (ISSA) 5000, General Requirements for Sustainability Assurance Engagements. It also committed to an extensive, high-level outreach plan to ensure broad stakeholder input to improve both the quality of and trust in the final standard. This plan included in-person roundtables around the world, virtual webinars for global audiences, and regional and national meetings with regulators and oversight bodies.
These are the results of this unprecedented outreach campaign:
The FAQ compilation addresses a variety of questions, including how the concept of materiality applies to sustainability reporting and assurance; the definition of double materiality; and how an assurance practitioner considers an organization’s “materiality process” during a sustainability assurance engagement, among other questions and answers.
The comment period for proposed ISSA 5000 is open until December 1, 2023. To promote broad and diverse participation in the ongoing public consultation, the IAASB has developed a Stakeholder Survey, which may be especially useful for stakeholders wishing to share less technical or overall feedback, and a Response Template.
For further details and updates, visit the IAASB website: iaasb.org/ISSA5000