This guidance was written for all organizations, regardless of their size or structure, private or public, to support the accountancy profession’s facilitation of sustainable organizations, financial markets, and economies by providing guiding principles to manage the complexities of performing a robust project and investment appraisal. Greater rigor in the appraisal and decision process can be achieved by using the principles as a benchmark against which to assess an organization’s current practice.
A Guide for Professional Accountancy Organizations
A strong and well-governed professional accountancy organization (PAO) produces and sustains a strong accountancy profession that is able to serve the public interest and contribute to economic stability and growth. A successful PAO gains much of its strength from the sense of identity, benefits, and rights that members derive from membership; and from the contributions that individual members and firms make to the PAO in recognition of its public interest perspective.
This third edition of the guide features enhancements to the two sample manuals, as well as other refinements for clarity and consistency with International Standard on Quality Control (ISQC) 1. The guide contains the requirements set out in ISQC 1 in addition to implementation guidance, including discussion material and an integrated case study that can be used as the basis for education and training.
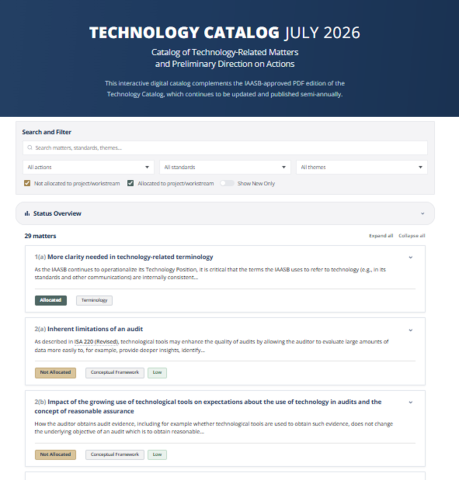
The International Auditing and Assurance Standards Board (IAASB) today launched an interactive digital version of its Technology Catalog, making it easier for stakeholders to explore emerging technologies and related developments affecting audit and assurance—and see how the IAASB is considering them across its work program.
The new interactive format makes the Catalog more accessible and easier to navigate. Stakeholders can sort and filter technology topics, explore dashboard summaries, and see connections between emerging developments and the IAASB’s standard-setting and other activities.
“Technology continues to change how information is produced, used, audited, and assured,” said Tom Seidenstein, IAASB Chair. “The Technology Catalog helps us systematically monitor these developments and consider their implications for our standards and our work. This new interactive format also gives stakeholders greater visibility into what we are seeing and how we are responding.”
The interactive Catalog currently reflects the third edition, which includes:
Five new technology and assurance topics, including crypto-assets, cybersecurity threats affecting entities, and potential new or evolving assurance engagements.
Updated information on active IAASB projects and workstreams, providing greater insight into how technology-related matters are being considered across the IAASB’s activities.
A refined structure and categorization, making it easier to follow how technology matters can progress from emerging issues to active standard-setting and implementation or application support activities.
The IAASB updates and publishes the Technology Catalog semi-annually, with updates reflected in both the PDF edition and the interactive Catalog. This helps ensure the Catalog remains a current, practical resource for stakeholders and a transparent record of how the IAASB is monitoring and responding to technological developments affecting audit and assurance.