• IAASB Releases COVID-19 Related Guidance for Auditor Reporting

    English

    Today the IAASB released COVID-19 Pandemic-related guidance for auditors to consider when issuing an auditor's report on the completion of the audit of financial statements.

    The guidance document can be found HERE.

    In the IAASB’s ongoing response to COVID-19, guidance related to Going Concern and Subsequent Events have also been issued, and more information and helpful links can be found on the IAASB’s COVID-19 Webpage.

  • IAASB Releases Revised Work Plan Table for 2020-2021

    English

    To account for COVID-19’s impact on the International Auditing and Assurance Standards Board’s (IAASB) work, its staff capacity to deliver, and the capacity of the IAASB’s stakeholders to participate in consultations and to implement new standards, the IAASB has reconsidered the timelines for its projects in 2020. The Revised Detailed Work Plan Table for 2020-2021 sets out a description of the changes that have been made and the revised timelines for 2020 and 2021 (as applicable).

    “Like many others, we revised our Work Plan to respond to realities imposed by the COVID-19 pandemic,” noted Tom Seidenstein, Chair of the IAASB. “Our approach directs capacity to emerging  public interest needs and accounts for the capacity of our stakeholders, volunteer Board Members, and staff. We will also continue to monitor whether further changes are needed."

  • IAASB Issues Support Material For Audit Documentation when Using Automated Tools and Techniques

    English

    The Technology Working Group (TWG) of the International Auditing and Assurance Standards Board (IAASB) today released non-authoritative support material related to the auditor’s documentation when using automated tools and techniques (ATT), such as data analytics, robotics automation processes or artificial intelligence applications. 

    The publication intends to assist auditors in understanding how the use of ATT during an audit engagement may affect the auditor’s documentation in accordance with International Standard on Auditing (ISA) 230, Audit Documentation, and the documentation requirements of other relevant ISAs.

    The publication does not constitute an authoritative pronouncement of the IAASB, nor does it amend, extend or override International Standard on Quality Control (ISQC) 1 or the ISAs, the texts of which alone are authoritative. Reading the publication is not a substitute for reading ISQC 1 or the ISAs.

    Click here to learn more.

     
  • IAASB’s New Strategy and Work Plan Focuses on Increased Agility, Enhanced Coordination, and a Priority on Responding to Emerging Challenges

    English

    Today, the International Auditing and Assurance Standards Board (IAASB) published its Strategy for 2020‒2023 (the Strategy) and Work Plan for 2020‒2021 (the Work Plan).

    The strategy, developed through extensive external consultation over two years, looks to build sustained trust in financial and other reporting through high-quality audits, assurance, and related services engagements. The IAASB also recognizes the need to address the impact of technology, demands relating to changing reporting needs (including demands in relation to non-financial reporting), and changing expectations for the audit.

    “The IAASB recognizes the significant challenges facing the audit profession and the standards that govern it. This Strategy and Work Plan provides an important compass for our organization to address these challenges in a highly responsive and innovative manner,” said Tom Seidenstein, Chair of the IAASB. “We will inevitably need to adapt over the strategy’s four-year period, but the emphasis on the public interest, innovation and agility, and collaboration should remain relevant.”

    Consistent with governance requirements, the Public Interest Oversight Board (PIOB), the IAASB’s independent oversight body, concluded at its March 2020 meeting that the IAASB developed its Strategy and Work Plan in accordance with due process and with proper regard for the public interest.

    Key IAASB Strategy and Work Plan Elements

    The strategy sets three strategic objectives to focus IAASB priorities and resources during 2020‒2023:

    1. Increase the emphasis on emerging issues to ensure that the IAASB International Standards provide a foundation for high-quality audit, assurance and related services engagements
    2. Innovate the IAASB’s ways of working to strengthen and broaden our agility, capabilities, and capacity to do the right work at the right time
    3. Maintain and deepen relationships with stakeholders to achieve globally relevant, progressive and operable standards

    The Work Plan describes, at the time of the December 2019 approval, how the IAASB intends to increase its focus on emerging issues, while completing the existing work already committed to and underway. In the Work Plan, the IAASB anticipates standard-setting projects on going concern, fraud, and audit evidence, and work to address the needs of auditors of Less Complex Entities, among other topics. To support an evidence-based and structured consideration of new topics, the IAASB Work Plan highlights a new Framework for Activities, comprising several key components, to help the IAASB develop informed and targeted responses to address emerging issues and topics of global relevance.

    Impact of the COVID-19 Pandemic on the Strategy and Work Plan

    While the IAASB approved its strategy before the pandemic, the three strategic objectives remain relevant. The IAASB has used these strategic objectives to help prioritize its crisis response. For example, the IAASB has developed, and is continuing to develop, guidance on audit considerations in response to the pandemic. The IAASB is enhancing its interactions with national audit standard-setters, regulators, and independent audit oversight regimes.

    At the same time, the IAASB recognizes that its Work Plan and timelines may need to adapt as new priorities emerge, the pandemic and associated restrictions impact our ability to work, and stakeholder capacity for change becomes constrained. In the coming weeks and months, the IAASB will consider potential impacts and consult, as appropriate, with the PIOB, the IAASB Consultative Advisory Group, and other stakeholders.

    The outcome of IAASB consultations could lead to the reprioritization of topics and changes in the timing of projects and consultation efforts. The IAASB will post any changes on its Website.


  • Special Edition eNews: Proposed Revisions to ISA 330, ISA 500, and ISA 520

    English


  • IAASB Launches Interactive Digital Technology Catalog

    New York, New York English

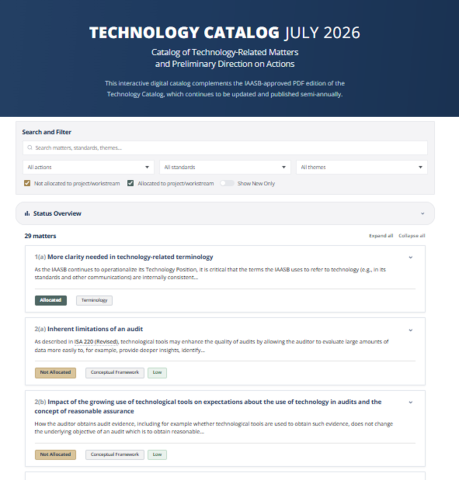
    The International Auditing and Assurance Standards Board (IAASB) today launched an interactive digital version of its Technology Catalog, making it easier for stakeholders to explore emerging technologies and related developments affecting audit and assurance—and see how the IAASB is considering them across its work program.

    Image
    IAASB Digital Tech Catalog screengrab

    The interactive Catalog complements the PDF edition of the Technology Catalog, which is formally cleared by the IAASB and published semi-annually.

    The new interactive format makes the Catalog more accessible and easier to navigate. Stakeholders can sort and filter technology topics, explore dashboard summaries, and see connections between emerging developments and the IAASB’s standard-setting and other activities.

    “Technology continues to change how information is produced, used, audited, and assured,” said Tom Seidenstein, IAASB Chair. “The Technology Catalog helps us systematically monitor these developments and consider their implications for our standards and our work. This new interactive format also gives stakeholders greater visibility into what we are seeing and how we are responding.”

    The interactive Catalog currently reflects the third edition, which includes:

    • Five new technology and assurance topics, including crypto-assets, cybersecurity threats affecting entities, and potential new or evolving assurance engagements.
    • Updated information on active IAASB projects and workstreams, providing greater insight into how technology-related matters are being considered across the IAASB’s activities.
    • A refined structure and categorization, making it easier to follow how technology matters can progress from emerging issues to active standard-setting and implementation or application support activities.

    The IAASB updates and publishes the Technology Catalog semi-annually, with updates reflected in both the PDF edition and the interactive Catalog. This helps ensure the Catalog remains a current, practical resource for stakeholders and a transparent record of how the IAASB is monitoring and responding to technological developments affecting audit and assurance.

    Explore the interactive Technology Catalog here.

    About the IAASB

    The International Auditing and Assurance Standards Board develops auditing, assurance, related services, and quality management standards and guidance in the public interest that support consistent performance of quality engagements. Along with the International Ethics Standards Board for Accountants, the IAASB is part of the International Foundation for Ethics and Audit. The Public Interest Oversight Board oversees IAASB and IESBA activities and the public interest responsiveness of the standards. For copyright, trademark, and permissions information, please visit Permissions.

    Work Enhanced Resource Provides Greater Visibility into Emerging Technologies and Their Impact on Audit and Assurance

  • IAASB eNews October 2026

    English

    In this eNews you will find:

    • Highlights from our September meeting
    • 2026 IAASB Handbook
    • Audit Evidence and risk response proposals
    • Our plans for Q4 2026
    • Key dates for this quarter
    Highlights from Our September Meeting

    Topics we discussed at our September 2026 meeting included:

    • Strategy and Work Plan 2028–2031 – We discussed the responses to the joint stakeholder survey that was published earlier this year with the International Ethics Standards Board for Accountants (IESBA). Survey responses will inform an IAASB consultation paper on the Strategies and Work Plan for 2028–2031, expected in early 2027.

    • Technology Quality Management – We discussed drafts of the first two guides in the Technology Quality Management guide series. The first will be on common conceptual foundation and the second on firm-level quality management before deployment.

    • ISA 500 Series (Project Stage: Exposure Draft Development) – We discussed the first full drafts of Proposed ISA 501 (Revised) as it relates to inventory, Proposed ISA 505 (Revised), External Confirmations, and significant proposed conforming and consequential amendments. 

    • Post Implementation Review of ISA 540 (Revised), Auditing Accounting Estimates and Related Disclosures – We discussed responses to the online survey for the post-implementation review of ISA 540 (Revised) and the proposed direction for the way forward.

    • Other Assurance Engagements – We discussed the initial findings from information-gathering activities, which will inform a final report and recommendations expected at our December 2026 meeting.

    Recordings of the September 2026 meeting are available on our YouTube channel; more information on our projects can be found on the Latest on Our Projects web page.

    2026 IAASB Handbook

    The 2026 edition of our Handbook of International Quality Management, Auditing, Review, Sustainability and Other Assurance, and Related Services Pronouncements was released last week.

    The following standards, which become effective in December 2026, are included in the 2026 Handbook:

    • ISA 240 (Revised), The Auditor’s Responsibilities Relating to Fraud in an Audit of Financial Statements

    • ISA 570 (Revised 2024), Going Concern

    • ISSA 5000, General Requirements for Sustainability Assurance Engagements

    • Narrow Scope Amendments resulting from revisions to the definitions of listed and public interest entities in the International Code of Ethics for Professional Accountants (including International Independence Standards), issued by the IESBA

    • Narrow Scope Amendments to IAASB standards arising from the IESBA’s Using the Work of an External Expert project

    Share Your Views on Our Audit Evidence and Risk Response Proposals

    In early August, we opened a public consultation on proposed revisions to ISA 330, ISA 500, and ISA 520 to enhance the risk-based audit framework and address technological advances. Comments are requested by December 15, 2026. 

    Building on recent revisions—including ISA 315 (Revised 2019)—the proposals further embed, clarify, and strengthen a principles-based, risk-based audit framework. They also address the increased use of technology in business, financial reporting, and auditing.

    • Establish a comprehensive basis for auditors' judgments about audit evidence.

    • Strengthen auditors' responses to assessed risks.

    • Reinforce professional skepticism and professional judgment throughout the audit.

    • Support innovation while remaining principles-based rather than technology-specific.

    We have also developed a package of resources to support stakeholder, including:

    • A user consultation survey, which offers users of financial statements a targeted way to provide feedback

    • A two-part global webinar series on September 29–30 and October 5–7 in which we explore key aspects of the proposals and include live Q&A. Recordings of the webinars will be available in our YouTube channel after they air.

    • A technical video series that takes a deeper look at key aspects of the proposed revisions.

    • A slide deck to help stakeholders engage with their members and stakeholders on our proposed revisions.

    • A supplemental table mapping key changes to the original project objectives.

    Access all Exposure Drafts and related materials on the IAASB website: www.iaasb.org/AuditEvidence-RiskResponse 

    Looking Ahead: Our Plans for Q4 2026

    Technology Quality Management

    We have been working on developing the non-authoritative guide series on applying the IAASB’s quality management standards to AI-enabled technological tools. Guide 1, Common Conceptual Foundation is anticipated in November, subject to approval at our October 28, 2026 mid-quarter meeting.

    ISSA 5000 on Sustainability Assurance

    As we continue supporting adoption and implementation of ISSA 5000, we are developing additional frequently asked questions (FAQ) and updating jurisdictional adoption information. In Q4 2026, we plan to release FAQs on general matters, including matters which were not addressed in other implementation guidance, and an IAASB-IESBA joint FAQ. Access resources on the dedicated ISSA 5000 web page.

    Key Dates for this Quarter

    • On October 20 and 21 our Stakeholder Advisory Council will meet in New York. You can find more information about this meeting on the October 2026 meeting web page. This meeting will be livestreamed on our YouTube channel. 
    • On October 22, we will meet with our Jurisdictional Standard Setters.

    • On October 28, the IAASB will have a virtual mid-quarter meeting in which we will discuss guide 1 of the Technology Quality Management guide series and Proposed ISA 501 (Revised) as it relates to inventory. The meeting agenda and meeting papers will be available on our October 2026 meeting web page approximately one week in advance of the meeting. This meeting will be livestreamed on our YouTube channel.
    • From December 7 to 10, the IAASB will meet in Madrid. The meeting agenda and meeting papers will be available on our December 2026 meeting web page approximately two weeks in advance of the meeting. This meeting will be livestreamed on our YouTube channel.